

















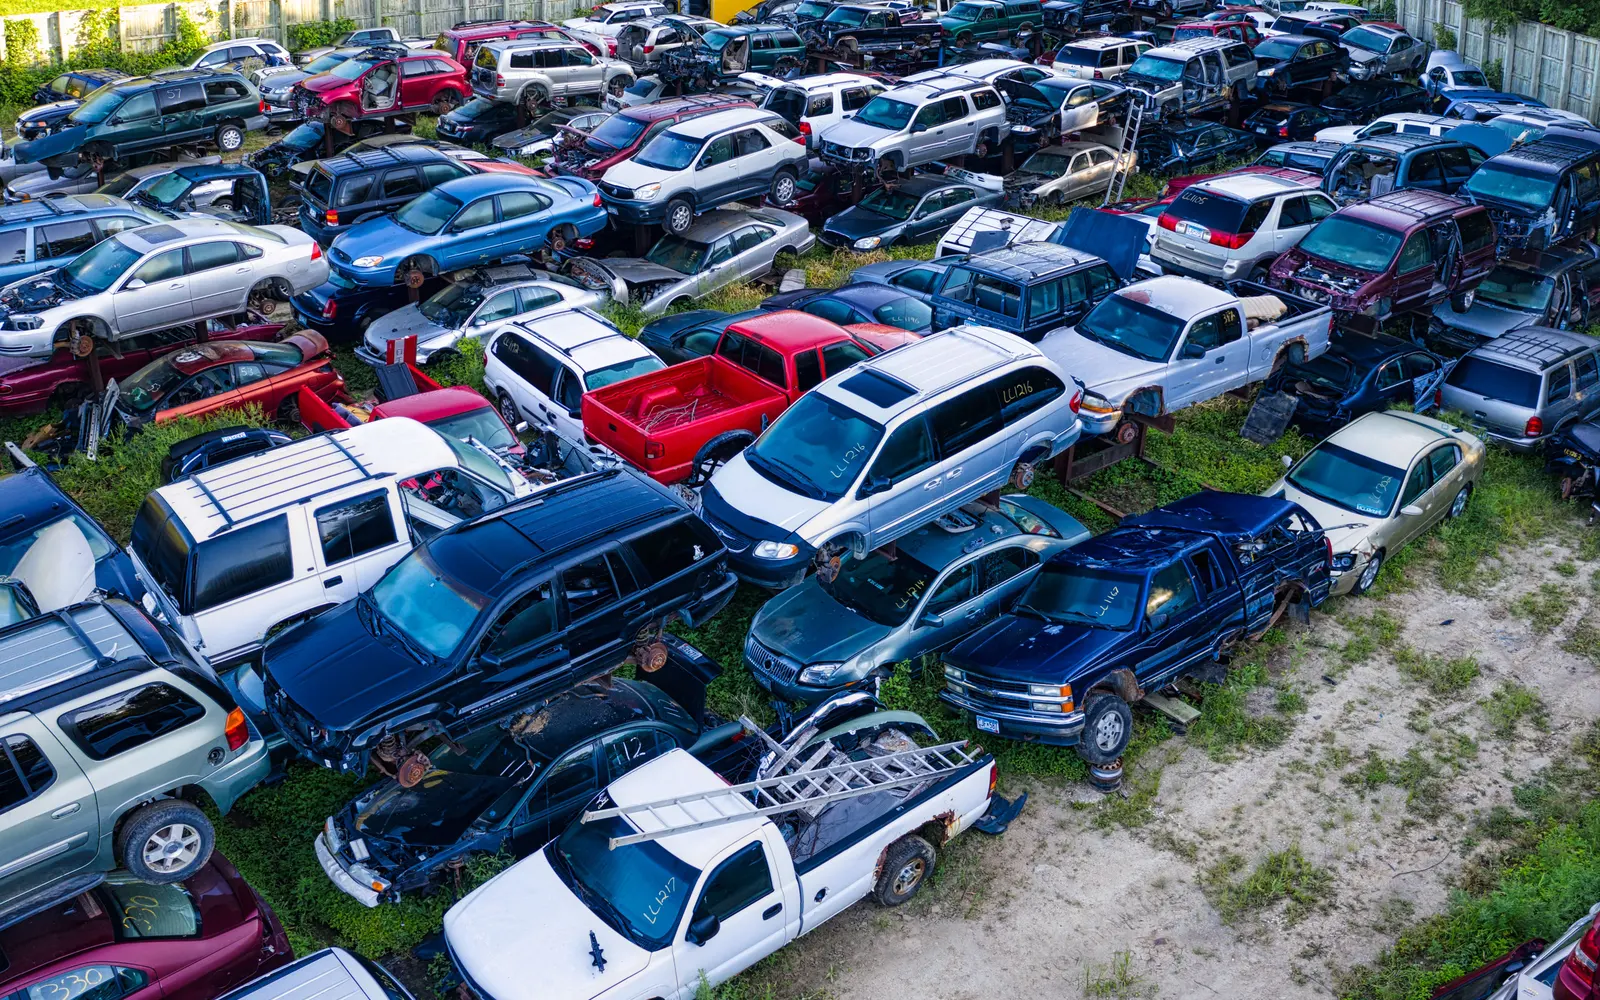
Your car got totaled. The offer came in low. You want to fight it.
Fight it. Just get the car off the storage lot first, because the day that offer lands, the lot bill quietly becomes yours.
Oregon’s Division of Financial Regulation says it in one sentence on its own consumer page. “Usually, the company pays the storage fees up to the day it makes an offer. If you do not accept the offer, you may be responsible for the fees from that time forward.”
Maine’s Bureau of Insurance is blunter. The company “is not obligated to pay for storage fees that continue to accrue while you try to resolve a disputed claim.”
Read that twice. The thing you’re disputing is the insurer’s number. The cost of disputing it is a daily charge from a third party who did nothing wrong and has no reason on earth to stop the meter.
How much? Texas is one of the states that caps it, so use Texas as the cheap version. A licensed vehicle storage facility can charge up to $22.85 a day for a car 25 feet or shorter, and the state says the fee applies “for any part of the day.” A day begins and ends at midnight. Drop a car off at 11 p.m. and the lot has earned a full day by 11:01. Add up to $50 for mailing you the notice that your car is there, plus an impoundment fee that “may not exceed $20.”
That is the regulated, consumer-protective version.
Two weeks of back-and-forth with an adjuster isn’t a long dispute. It’s a normal one. Fourteen days at $22.85 is $319.90. Thirty days is $685.50. Argue over $1,500 of valuation for a month and you’ve handed almost half of it to a fenced lot in a field.
The rental dies too. Oregon describes the substitute-car window as running “from the date of the accident until one or two days after the company makes an offer on the totaled vehicle.” Not until you agree. Not until you’ve bought a replacement. One or two days after the offer.
Here’s the move, and it takes an afternoon.
The day the offer lands, get the car off that lot. Your driveway, a relative’s driveway, the body shop that already has it, anywhere that isn’t billing by the night. Call the lot first and get the running total in writing so nobody invents a number at the gate.
Then take the money that isn’t in dispute. Oregon says that if you transfer ownership while negotiations continue, “the company must pay you the amount that is not in dispute.” Take it. Do not cash anything stamped as full and final settlement while you’re still arguing, because cashing it ends the argument.
One more clock. In Oregon, once the company has your car, “after 14 days, the company may sell your vehicle.” If you want to buy back the salvage, say so before day 14, not after.
Now go win the valuation fight on its own terms. Your policy has an appraisal clause, and one driver used hers to collect more than $4,000 after a court shut down the class action she’d filed. If your carrier’s opening number and its attitude both tell you the same thing, re-shop the policy once the claim closes.
Fight the number. Just don’t rent a parking space to do it.
How Candid Yak makes money. Some of the products we write about pay us if you apply or sign up through our links. That never changes our verdict, our rankings, or the numbers in this article. We call a bad deal a bad deal whether it pays us or not. Some brands shown in our comparison tools are placeholder examples while we finalize partner agreements, and we label them as such.